FHA BUYERS
The FHA vs. Conventional Decision Sheet
Your credit profile, down payment and expected time in the home can change which loan fits best. Compare the actual costs over your likely ownership period, not just the first payment.
A personal comparison worksheet for the choices that affect your cost today and over the years you expect to keep the loan.
Instant access. No email required. Two pages, including a printable worksheet.
Request an FHA comparison conversation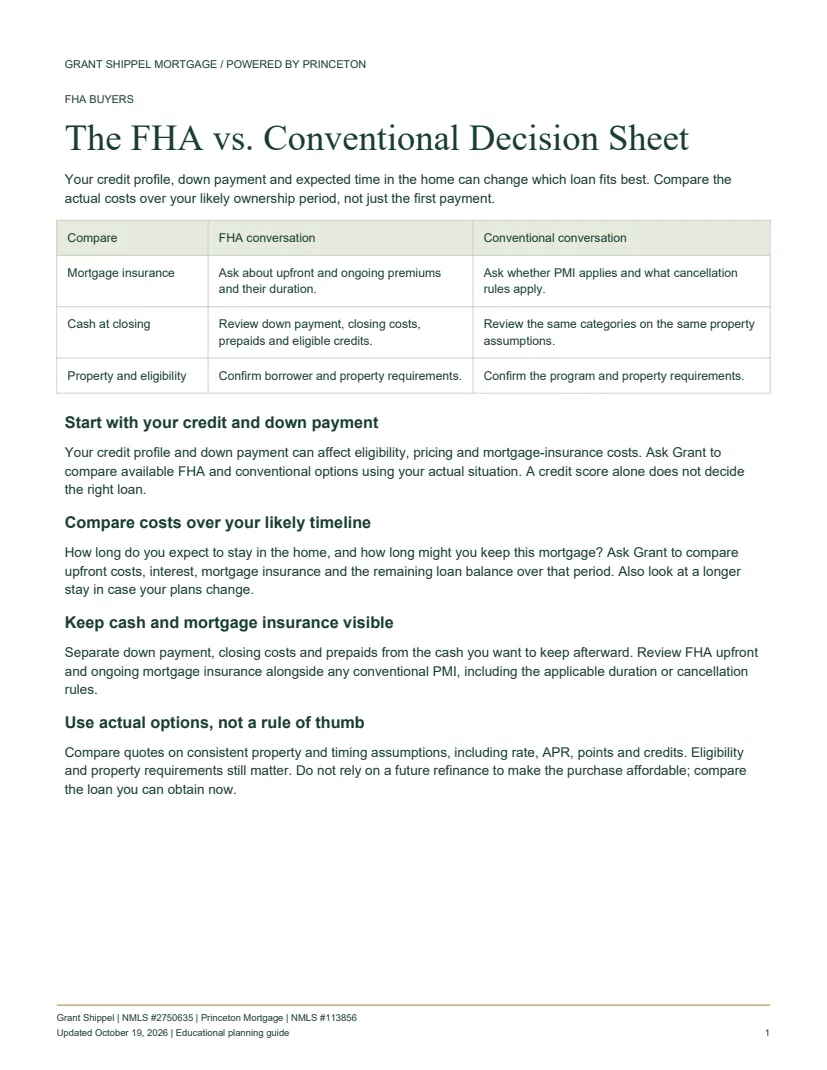
The options to discuss
| Compare | FHA conversation | Conventional conversation |
|---|---|---|
| Mortgage insurance | Ask about upfront and ongoing premiums and their duration. | Ask whether PMI applies and what cancellation rules apply. |
| Cash at closing | Review down payment, closing costs, prepaids and eligible credits. | Review the same categories on the same property assumptions. |
| Property and eligibility | Confirm borrower and property requirements. | Confirm the program and property requirements. |
Start with your credit and down payment
Your credit profile and down payment can affect eligibility, pricing and mortgage-insurance costs. Ask Grant to compare available FHA and conventional options using your actual situation. A credit score alone does not decide the right loan.
Compare costs over your likely timeline
How long do you expect to stay in the home, and how long might you keep this mortgage? Ask Grant to compare upfront costs, interest, mortgage insurance and the remaining loan balance over that period. Also look at a longer stay in case your plans change.
Keep cash and mortgage insurance visible
Separate down payment, closing costs and prepaids from the cash you want to keep afterward. Review FHA upfront and ongoing mortgage insurance alongside any conventional PMI, including the applicable duration or cancellation rules.
Use actual options, not a rule of thumb
Compare quotes on consistent property and timing assumptions, including rate, APR, points and credits. Eligibility and property requirements still matter. Do not rely on a future refinance to make the purchase affordable; compare the loan you can obtain now.
Your conversation worksheet
Use these prompts to prepare. Grant will build your scenarios personally after speaking with you.
Property / purchase target / timing
Expected years in home / years keeping this mortgage
Credit profile or concerns to discuss securely with Grant
Down payment / total purchase cash / cash to preserve
FHA: payment, insurance, upfront costs (Grant to fill)
Conventional: payment, insurance, upfront costs (Grant to fill)
Costs and remaining balances at my planned time horizon
What changes if I stay longer or cannot refinance?
Before your conversation
- Ask for both options if both are available for your situation.
- Use your actual credit, down payment and property assumptions.
- Include upfront charges, mortgage insurance and cash reserves.
- Compare the expected ownership period and a longer stay.
- Review actual Loan Estimates and unresolved loan conditions.
Common questions
Is FHA automatically the best first-home loan?
No. Ask for a comparison based on your actual eligibility, cash, costs and plans.
Can a guide tell me whether I qualify?
No. This worksheet organizes the conversation; Grant and the lender review the actual loan and property.
Request an FHA comparison conversation
Tell Grant what you are planning. He will review your goals, discuss the next steps and prepare your financing options personally.
Please use the secure process Grant provides for financial documents. This guide does not determine eligibility or produce a quote.
Further reading
YOUR GOALS. A CLEARER PLAN.
Let’s put your next move in focus.
A home, a refinance or an investment. Start with a conversation about what matters to you.